
The short answer
The 2000 reform did not invent Australian takeover regulation or create a Panel where none had existed. It changed who could bring a dispute, the forum used during a live bid and the practical machinery for reaching a commercially relevant decision in time.
Chronology
A timeline of the turning points
An earlier statutory body
A stand-alone Corporations and Securities Panel begins under a narrower referral model.
Practical preparation
Draft procedures and executive arrangements are announced ahead of commencement.
Wider jurisdiction takes effect
Interested parties gain access to a main forum for live takeover disputes.
First applications
The anniversary record dates the first applications under the expanded jurisdiction.
Further legal development
Renaming, replacement legislation and later jurisdiction amendments follow.
A decade assessed
The Panel publishes its own account of performance and remaining institutional work.
The earlier body existed, but its access was much narrower
A stand-alone Corporations and Securities Panel had existed since 1991. Applications initially depended on the corporate regulator rather than any interested bidder or shareholder being able to approach it directly. The later reform therefore altered an existing institution’s position within takeover regulation, not simply its name.
Parliament’s subsequent oversight account identifies concern that court proceedings during a bid could become a tactical source of delay. Timing mattered because a legal argument could affect a transaction before shareholders reached a commercial decision. A workable alternative needed to address the dispute while that decision remained meaningful.
March 2000 changed access and the principal forum
The CLERP legislation’s expanded regime began on 13 March 2000. Interested parties could seek intervention, and the Panel became the primary forum for disputes about a takeover bid during its currency. The 2 March preparation release shows the change approaching implementation: procedural rules were still exposed for comment when the new function was about to start.
Wider access was important in its own right. A bidder, target or affected investor no longer depended entirely on persuading a regulator to initiate the process. But access to a forum did not mean an automatic decision in an applicant’s favour. The institution still had to consider the circumstances, hear relevant submissions and decide whether intervention was warranted.
Commercial peer review required an operating organisation
Part-time members brought experience from banking, law and company boards. The historical model used three members for an individual application, supported by an executive. McKeon’s presidency provided institutional leadership; it did not make him the sole decision-maker in each dispute.
The preparation announcement also described permanent staff, rotating private-sector secondees and facilities enabling participation beyond Melbourne. These details explain how the model was meant to work. A panel of experienced names would not have been enough without people organising submissions, coordinating availability and supporting decisions within the short life of a transaction.
Unacceptable circumstances were not confined to punishing a breach
The historical guidance treated market effects and the principles governing control transactions as central. Informed shareholder choice, time to consider a proposal and confidence in the market were not interchangeable with the narrow question of whether someone had committed a specific statutory offence.
The superseded 2003 note expressly allowed unacceptable circumstances without a contravention. This historical distinction helps explain the reform’s commercial-policy emphasis. It did not authorise unlimited discretion or remove procedural obligations. Nor should a general account of its early principles be used as present-day transaction advice: legislation, guidance and jurisdiction continued to develop after commencement.
Early evaluation supports use, not an unqualified success claim
A university-hosted historical study summary reported 153 decisions in the first five years and a median application-disposal time of 14 days. Those figures describe a particular sample and period, not a guaranteed deadline. Independent legal reporting welcomed greater efficiency while also discussing the jurisdiction concerns raised by Glencore litigation.
The Panel’s own tenth-anniversary account likewise described substantial use and quick decisions, but it was an institutional self-assessment. Later amendments show that the framework was not legally finished in March 2000. The reform’s value lies in a concrete redesign of access and dispute resolution; judging every decision, cost saving or shareholder outcome would require evidence beyond these historical summaries.
Continue the chronology
Related history guides
Biography context
Explore Australia through connected lives
Simon McKeon
Place the presidency within law, investment banking, philanthropy and later board responsibilities.
Explore the biographiesCompare an institutional designTesla’s chair transition
Distinguish a governance structure’s adoption from proof of every desired outcome.
Explore the biographiesConnected biographies
A president within a wider statutory institution
1955–
Simon McKeon
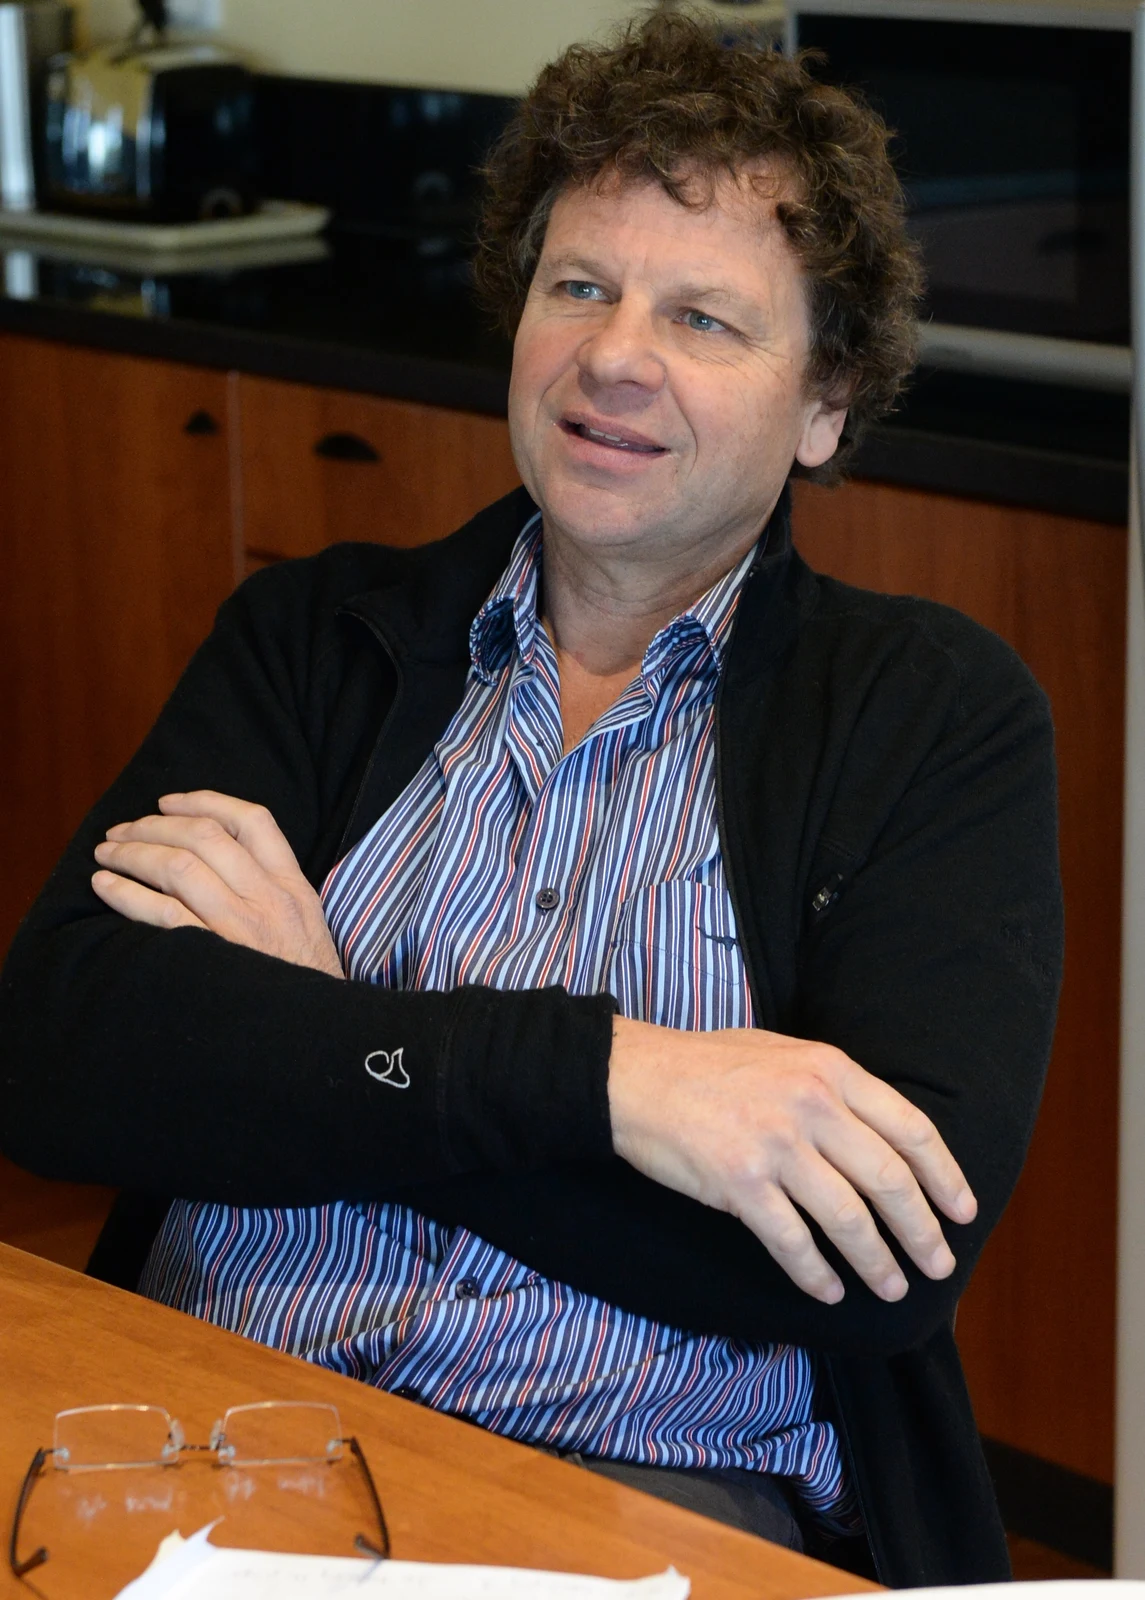
Investment banker, company director and former Takeovers Panel presidentSimon McKeon built a career in law and investment banking before dividing his working life between corporate and civic institutions. He led Australia’s Takeovers Panel through its expanded 2000 regime, chaired major organisations and became 2011 Australian of the Year. His later directorships also place him within difficult debates about board responsibility and public trust.Read biographyQuick answers
Common questions
- Was there no Panel before 2000?
- An earlier stand-alone Panel existed from 1991; the March 2000 regime substantially expanded its role and access.
- Did the president decide every case?
- No. Historical applications were decided by sitting panels of three members, with executive support.
- Did unacceptable circumstances always require a legal breach?
- No. The historical guidance expressly allowed intervention where circumstances were unacceptable without a contravention.
- Was 14 days a mandatory deadline?
- No. It was a reported median in a historical study, not a universal time guarantee.
Primary and institutional sources
How this history was checked
Actual Panel history, preparation, anniversary and superseded-guidance passages establish the historical mechanism. The parliamentary chapter, university-hosted study summary and independent legal report were available as indexed passages; direct requests were restricted, so neither the whole chapter/PDF nor the underlying empirical dataset is claimed read. Historical self-reported performance is distinguished from independent evaluation and from any present-day legal advice. This article was reviewed on 24 October 2026.
- Takeovers PanelLegislative framework and history: selected 1991, 1994, 2000, 2001 and 2007 entries
- Takeovers Panel2 March 2000: new jurisdiction, draft procedures, full-time executive and national participation
- Takeovers Panel12 March 2010: historical peer-review composition, first applications and the Panel’s own performance assessment
- Takeovers PanelSuperseded 17 September 2003 Guidance Note 1: selected overview and principles, used historically
- Parliament of AustraliaIndexed oversight chapter paragraphs 4.1–4.7: reasons for the 2000 regime and commercial-policy focus
- University of Melbourne-hosted historical legal bulletinIndexed first-page study summary: 2000–2005 decisions and reported median duration; not the underlying empirical dataset
- Lawyers WeeklyIndexed historical report: positive efficiency assessment and continuing Glencore jurisdiction concerns
- Starfish99 / Wikimedia CommonsComplete 18 July 2015 Mornington Peninsula portrait: initial own-work/self grant and sole file version
- Creative CommonsAttribution-ShareAlike 4.0 International